Britain’s Banking Export: The Blueprint Going Global
Sam Everington is taking Starling’s digital banking technology worldwide.
Engine by Starling
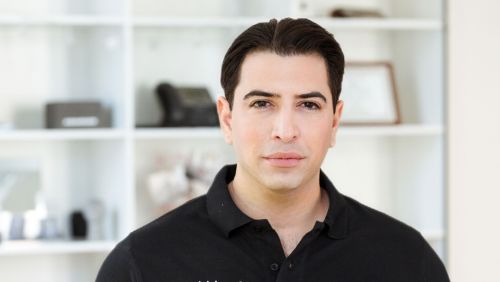
Sam Everington, CEO
Opinions expressed by Entrepreneur contributors are their own.
You're reading Entrepreneur United Kingdom, an international franchise of Entrepreneur Media.
Banking was built on decades of accumulated technology, regulation and infrastructure. But what if the next generation doesn’t have to inherit any of it? Sam Everington was there from the beginning of Starling, helping build the technology that powered one of Britain’s most influential digital banks. Today, as CEO of Engine by Starling, he is taking that architecture beyond Britain – from Romania and Australia to Canada, New Zealand and the Gulf – giving established institutions and emerging markets the chance to leapfrog legacy banking systems altogether. His ambition is bigger than exporting software. It is to export a blueprint: a radically different way to build, operate and scale a bank in the digital age. For this Global Entrepreneurship edition, Everington discusses why ageing infrastructure has become banking’s innovation ceiling, why emerging markets may have the advantage, and how British fintech could turn one of its greatest technological success stories into a global industry.
You were part of the team that built the technology powering Starling from the ground up. What did that experience teach you about how banking could be built differently?
I joined Starling back in 2016 as a software engineer, building the systems and apps behind the current account launch. What that experience really taught me is the difference in impact you can have between digitalising an existing process and designing the ideal journey from the customer and employee perspectives. Most banks are trying to bolt modern capability onto core foundations that’s twenty to forty years old. We got to start by focusing on solving the problem at hand – building on modern foundations that can operate intelligently, with full content to deliver real-time outcomes for everyone. That’s what convinced me the technology itself is the thing worth exporting.
Engine is now taking technology developed in Britain into international markets. What made you believe that what worked for Starling could work for banks around the world?
The proof point for me is Salt Bank in Romania. They went live on Engine in under twelve months – a fraction of the time it would take to compose component systems, yet alone build a proprietary core banking system from scratch. We’ve seen the same pattern with AMP in Australia, and are now delivering this for Tangerine in Canada and SBS Bank in New Zealand. The basic needs of people, families and businesses are the same everywhere. Further, almost every financial institution, regardless of geography, is dealing with the same rigid, ageing core infrastructure that is trying to meet the needs of ever modernising tech savvy customers. If the platform solved that once in the UK, there was every reason to believe it can solve it again elsewhere.
Could countries with less established banking infrastructure actually leapfrog the UK and build the next generation of banks faster?
Yes, and I think that’s an underappreciated point. Markets that don’t have the same decades of legacy spaghetti, don’t have to go through what I’d call the graveyard phase – the years banks spend trying, and frequently failing, to wrap their cores and replace all the components around. Incumbency can be as much a liability as an asset. A market building its banking infrastructure today can start where the world’s best digital banks are right now, rather than where we started decades ago.
What has expanding Engine internationally taught you about what Britain does well in fintech – and where it needs to improve?
Britain’s strengths include genuinely deep engineering talent and a regulatory environment which enables and encourages positive innovations. From real-time payments, to open banking, to AI in financial services, Britain has set new standards of expectation. London is where our tech stack was built, and it’s still where we’re investing, including our new HQ. While we’ve expanded beyond the UK, London remains a hub for innovation for us. Where British fintech needs to improve: for all the sleek apps UK neobanks have built, relatively few of us have become customers’ primary bank account. There is a huge opportunity in the UK for deepening customer relationships, with digital players expanding into primary accounts by building high-trust products customers can rely on.
The Middle East is investing heavily in financial innovation and building new digital economies. What opportunity do you see for Engine – and for British fintech more broadly – in the region?
The Middle East is a key region for Engine which is why we opened on our first Engine offices in the region last year. The GCC is deploying real capital, both financial and political support, into digital-first financial capabilities, which makes it a natural fit for a platform-led approach of enabling the uplift and rapid modernisation of existing institutions. We’re already running a genuinely international, cloud-native operation across Canada, Romania, Australia, and New Zealand — the Gulf is a real focus for us, and one where we feel both our technology and operating experience can have a significant impact on growth.
Are traditional banks becoming increasingly constrained by the legacy technology they have spent decades building around, and what does that mean for the future of banking?
The core banking software market is dominated by a handful of incumbent providers, and plenty of bank executives have tried to replace their core systems and failed. But legacy technology isn’t just a cost problem, it’s an innovation ceiling. It’s often expensive just to deploy real-time payments, yet alone give breadth of context to AI tools at speed, if the core underneath can’t support it. Everywhere we look, there are huge opportunities. Personalised and more human banking can be the future, at a scalable price-point, with technology built on the right foundations.
Could Engine ultimately become bigger than Starling – and if it does, what will you have changed about banking around the world?
We’ve set ourselves a target of £100m in annual recurring revenue, and we’re well on track to get there soon, off the back of our footprint across the UK, Canada, Romania, New Zealand and Australia. Engine is still a smaller business, relative to Starling’s overall Group revenue today, but it’s highly scalable and it’s asset-light. Engine gives the wider group real resilience and fee income, and all clients the benefits to learn from the experience of a community of like-minded banks. If we get this right, what I’ll have changed is proving that a handful of banks built on Engine can deliver both high levels of customer satisfaction and operating efficiency. We’ll have effectively exported the blueprint for what a well-built digital bank looks like, instead of every institution attempted to reinvent it.
Banking was built on decades of accumulated technology, regulation and infrastructure. But what if the next generation doesn’t have to inherit any of it? Sam Everington was there from the beginning of Starling, helping build the technology that powered one of Britain’s most influential digital banks. Today, as CEO of Engine by Starling, he is taking that architecture beyond Britain – from Romania and Australia to Canada, New Zealand and the Gulf – giving established institutions and emerging markets the chance to leapfrog legacy banking systems altogether. His ambition is bigger than exporting software. It is to export a blueprint: a radically different way to build, operate and scale a bank in the digital age. For this Global Entrepreneurship edition, Everington discusses why ageing infrastructure has become banking’s innovation ceiling, why emerging markets may have the advantage, and how British fintech could turn one of its greatest technological success stories into a global industry.
You were part of the team that built the technology powering Starling from the ground up. What did that experience teach you about how banking could be built differently?
I joined Starling back in 2016 as a software engineer, building the systems and apps behind the current account launch. What that experience really taught me is the difference in impact you can have between digitalising an existing process and designing the ideal journey from the customer and employee perspectives. Most banks are trying to bolt modern capability onto core foundations that’s twenty to forty years old. We got to start by focusing on solving the problem at hand – building on modern foundations that can operate intelligently, with full content to deliver real-time outcomes for everyone. That’s what convinced me the technology itself is the thing worth exporting.

Patricia Cullen • Features Writer
Entrepreneur Staff