The Next Trillion-Dollar Technology Trade Won’t Be AI Alone
UK investors are looking beyond AI to infrastructure, quantum and digital finance.
Moon Pursuit Capital
Utkarsh Ahuja
Opinions expressed by Entrepreneur contributors are their own.
You're reading Entrepreneur United Kingdom, an international franchise of Entrepreneur Media.
AI is still attracting enormous pools of capital. But the more important investment question
for 2027 is moving down the stack, into the infrastructure, science, security and financial rails
that make the next technology cycle possible.
The technology investment cycle is changing shape. McKinsey’s Technology Trends Outlook 2026 makes the shift visible. Five frontier technology areas: agentic software development, AI infrastructure and model architectures, AI for scientific discovery and engineering, the future of space technologies and the future of robotics, are on track to receive more than double the investment in 2026 compared with 2025. AI infrastructure spending itself doubled in a year, while energy technologies attracted almost $200bn in investment in 2025.
For investors, however, the lesson is not simply “put more money into AI”. The more useful question is: what sits underneath the AI boom, and what comes next? For the UK, that distinction matters. Britain does not need to win every layer of the technology stack. It needs to identify the layers where its existing strengths, capital markets, financial services, scientific research, engineering and legal infrastructure, can translate into durable ownership.
The UK already has a substantial base. According to the Department for Science, Innovation and Technology, UK digital and technology companies raised £8.3bn across 1,284 private-equity deals in 2025. Frontier technology firms accounted for £6.4bn of that, or 77% of total digital and technology equity investment. More than half of investment with known investor origin came from deals involving both UK and foreign investors, while 30.2% came from foreign-only deals.
That tells us two things. There is real international appetite for UK technology. But the next phase should be about converting that appetite into deeper domestic ownership, larger scale and more value captured in the UK. The first opportunity is AI infrastructure, but not simply another bet on an AI model. The market is increasingly revealing that AI is an infrastructure business. Compute, data centres, power, networking, chips and cooling systems are becoming strategic assets. Recent financing activity shows how capital-intensive that stack has become. UK AI cloud company Nscale reported $140.6m in revenue in the first half of 2026, up 1,252% year on year, while recording a $1.02bn net loss in its US IPO filing. The company also reported a 10-gigawatt power pipeline as it expands its AI infrastructure platform. That is not a reason to avoid AI infrastructure. It is a reason to understand its economics. Investors should separate businesses selling the “AI story” from businesses controlling scarce inputs. The latter may include power availability, specialised chips, high-performance compute, data-centre capacity, networking, cooling and the software that allocates compute efficiently.
In a capital-intensive market, scarcity can matter more than novelty. That distinction is especially relevant in Britain. The government’s June 2026 AI Hardware Plan committed £1.1bn, including £750m for a new national AI supercomputer and up to £150m through the British Business Bank for UK-based hardware companies. The implication is important: the UK is moving beyond experimentation, but adoption is still far from saturated. The next investment opportunity may therefore sit not only in building AI, but in the infrastructure and applications that allow businesses to use it at scale.
The second opportunity is quantum, not as a distant science project, but as an emerging security and infrastructure layer. Quantum investing is difficult because the timelines are longer and the commercial winners are less obvious than in software. That makes disciplined capital allocation more important, not less. The UK has committed up to £2bn to quantum projects and more than £500m to quantum computing research and development, with applications ranging from secure communications to medical diagnostics. For investors, the opportunity may not sit only in quantum computers themselves. It can emerge in the surrounding stack: quantum-safe cryptography, sensing, control systems, specialised components, networking and cybersecurity. This is where the convergence with digital assets becomes interesting. Blockchain networks are built on cryptographic assumptions. As quantum capabilities advance, cryptographic resilience becomes an investment issue rather than a purely technical one. That opens a market for infrastructure designed to make digital-asset systems more resistant to future attacks.
The third opportunity is digital financial infrastructure. Digital assets have often been discussed through the lens of crypto prices. For a financial centre such as London, the more consequential opportunity may be elsewhere. The UK is moving toward a new regulatory framework for cryptoassets, with firms able to begin applying for authorisation from 30 September 2026 and the new regime expected to come into force in October 2027.
At the same time, the UK is actively developing tokenised wholesale financial markets. The government’s 2026 Wholesale Digital Markets Champion report describes tokenised markets as an opportunity to shape the future infrastructure of global finance, while the UK’s wider digital-markets strategy includes work on tokenised funds, digital securities and stablecoin-enabled settlement. The interesting point is that this is no longer purely a retail crypto story. FCA research found that 8% of UK adults held cryptoassets in 2025, down from 12% in 2024. That shift reinforces a broader trend: the institutional opportunity in digital assets may be less about speculative ownership and more about the infrastructure around securities, custody, settlement, collateral and programmable finance.
The fourth opportunity is AI for scientific discovery. McKinsey’s data points to growing investment in AI that is being applied beyond chatbots and software workflows, including drug discovery, materials science and engineering. This is particularly important for the UK because Britain’s comparative strengths are unusually well aligned with this part of the AI economy: universities, research institutions, life sciences and advanced engineering.
The investment question is therefore shifting from “Which model wins?” to “Which scientific bottlenecks can AI make economically solvable?” A platform that helps discover a new molecule, battery material or industrial process can create value differently from a generic AI application. The route to commercialisation may be longer, but the underlying intellectual property can be more defensible. There is also a broader lesson here for UK investors: frontier technology is becoming increasingly interconnected. AI needs power. Power infrastructure increasingly depends on software and optimisation. Quantum changes the assumptions behind cybersecurity. Digital assets require secure cryptography and institutional market infrastructure. Robotics connects AI models to physical systems. Space generates new demand for compute, communications and autonomous systems. These are not separate investment themes forever. They are becoming one technology stack. That changes how investors should assess opportunities going into 2027. The old approach was to ask which sector was “hot”. The new approach is to ask where bottlenecks are forming. Look at capital intensity. Look at scarce resources. Look at switching costs. Look at regulatory pathways. Look at whether a technology can become embedded in infrastructure that customers cannot easily replace.
The UK does not need to replicate Silicon Valley to participate in the next technology cycle. It needs to connect its existing assets more effectively: London’s capital markets, world-class universities, engineering capability, financial institutions and an increasingly sophisticated technology ecosystem. McKinsey’s outlook suggests that frontier technology investment is accelerating. The opportunity for the UK is to ensure that capital is not simply following the headline technology of the moment, but identifying the infrastructure, security and intellectual property that can compound through multiple technology cycles.
For 2027, that is where I would focus the investment conversation: not on predicting the next fashionable sector, but on finding the systems that every fashionable sector will eventually need.
AI is still attracting enormous pools of capital. But the more important investment question
for 2027 is moving down the stack, into the infrastructure, science, security and financial rails
that make the next technology cycle possible.
The technology investment cycle is changing shape. McKinsey’s Technology Trends Outlook 2026 makes the shift visible. Five frontier technology areas: agentic software development, AI infrastructure and model architectures, AI for scientific discovery and engineering, the future of space technologies and the future of robotics, are on track to receive more than double the investment in 2026 compared with 2025. AI infrastructure spending itself doubled in a year, while energy technologies attracted almost $200bn in investment in 2025.
For investors, however, the lesson is not simply “put more money into AI”. The more useful question is: what sits underneath the AI boom, and what comes next? For the UK, that distinction matters. Britain does not need to win every layer of the technology stack. It needs to identify the layers where its existing strengths, capital markets, financial services, scientific research, engineering and legal infrastructure, can translate into durable ownership.

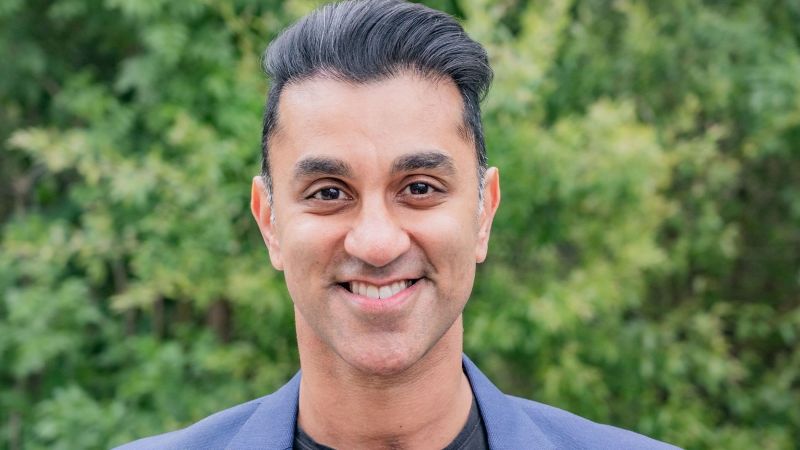
Utkarsh Ahuja • Founder & Managing Partner, Moon Pursuit Capital
Utkarsh Ahuja, Founder & Managing Partner of Moon Pursuit Capital